
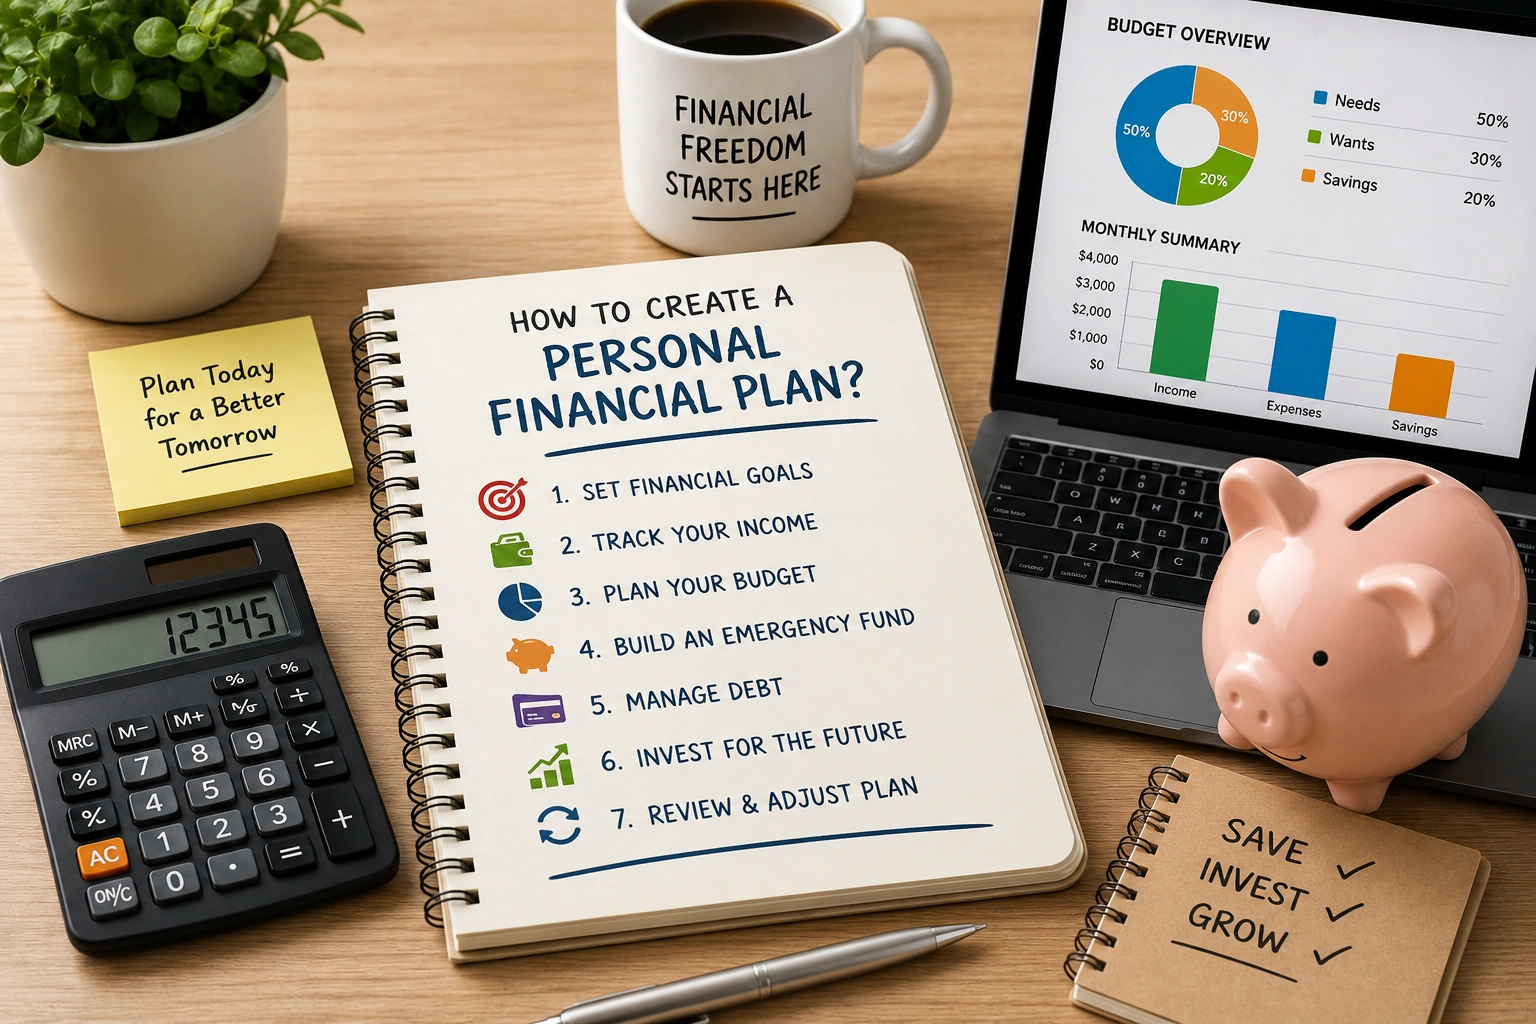
A personal financial plan provides a roadmap for managing income, expenses, savings, debt, and long-term goals. Without a clear plan, it can be difficult to know whether your money is moving toward the future you want. Creating a financial plan does not require complicated financial knowledge. By understanding your current situation, setting realistic goals, and reviewing your progress regularly, you can develop a practical strategy for managing your money.
Understand Your Current Financial Situation
The first step is to determine where you currently stand financially. List your sources of income and regular expenses, including housing, utilities, food, transportation, subscriptions, insurance, and other recurring costs.
You should also review savings, investments, outstanding debts, and other financial obligations. This provides a clear picture of your financial position.
A realistic assessment is important. Avoid estimating expenses based on what you hope to spend. Using actual spending records can make your financial plan much more useful.
Set Clear Financial Goals
Once you understand your current situation, identify what you want to accomplish. Financial goals can be short-term, medium-term, or long-term.
Short-term goals might include building emergency savings or paying off a small debt. Medium-term goals could include purchasing a vehicle or saving for education. Long-term goals might involve retirement or building significant wealth.
Make your goals specific and measurable. Instead of saying, “I want to save more,” determine how much you want to save and by when.
Create a Realistic Budget
A budget is one of the foundations of a personal financial plan. It helps you determine how much money comes in and where it goes.
Separate essential expenses from discretionary spending. Essentials may include housing, utilities, groceries, transportation, and required payments. Discretionary spending might include entertainment, dining out, shopping, and subscriptions.
A good budget should be realistic enough to maintain. Extremely restrictive plans can be difficult to follow over time.
Build an Emergency Fund
Unexpected expenses can disrupt even a well-organized financial plan. An emergency fund can provide a financial cushion for situations such as urgent repairs, unexpected bills, or temporary income loss.
Keep emergency savings accessible and separate from money intended for long-term investments. The appropriate amount depends on your circumstances, income stability, expenses, and personal needs.
Manage Debt Strategically
Debt should be an important part of your financial plan. Make a list of outstanding balances, interest rates, and required payments.
Prioritize making required payments on time and consider strategies for reducing high-cost debt. Paying down expensive debt can free up money that can later be directed toward savings and long-term goals.
Avoid taking on unnecessary new debt simply to maintain a lifestyle that your current income cannot comfortably support.
Plan for Long-Term Goals
Long-term financial goals require consistency. Depending on your circumstances, you may consider appropriate investments to support objectives such as retirement or long-term wealth accumulation.
Investment decisions should reflect your time horizon, financial goals, and tolerance for risk. Diversification can also be an important consideration when building a long-term portfolio.
Because financial circumstances differ widely, professional financial advice may be useful for more complex decisions.
Protect Your Finances
Financial planning is not only about saving and investing. Protection is also important. Review relevant insurance coverage and consider how unexpected events could affect your finances.
Keeping important financial documents organized and maintaining appropriate account security can also help protect your financial position.
Track Your Progress
A financial plan should not be created once and forgotten. Review your budget, savings, debt, and goals regularly.
Your income or expenses may change, and priorities can evolve. A new job, major purchase, family change, or change in financial responsibilities may require adjustments.
Regular reviews help ensure that your plan remains relevant.
Stay Consistent
The most effective financial plans are usually based on sustainable habits rather than quick fixes. Automating savings, monitoring spending, reducing unnecessary expenses, and regularly reviewing goals can make financial management easier.
Creating a personal financial plan gives your money a clear purpose. By understanding your finances, setting measurable goals, budgeting carefully, preparing for emergencies, managing debt, and planning for the future, you can build a structured approach to financial security and long-term financial well-being.